
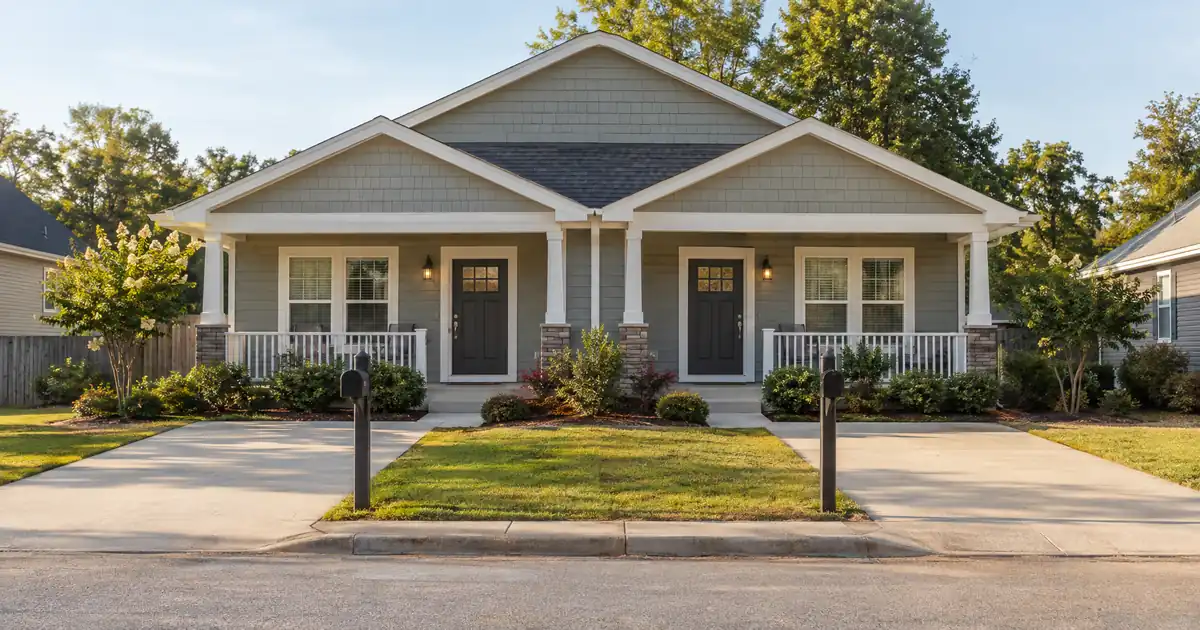
The Quick Read: Present the property as a legal two-unit duplex first and a co-living operation second, because a DSCR lender sizes the loan on one rent opinion per unit, not on the sum of every room lease. Confirm that a program accepts rent-by-room before you pay for an appraisal, and treat room-by-room income as upside rather than qualifying income.
- Check program eligibility first. Many DSCR programs restrict or exclude rent-by-room, so acceptance is a program question, not a DSCR-wide rule.
- Expect two rent figures, one per unit, from the appraiser. Rooms inside a unit sit below that level.
- Document the conversion: permits, final sign-offs, and certificate of occupancy status.
- Show that the duplex would still work as a standard long-term rental, in case room income is not counted.
- Clearing coverage is not positive cash flow. Co-living carries higher operating costs that DSCR never measures.
The rest of this piece walks through that sequence in order. For the broader mechanics behind the ratio, Lendmire’s complete DSCR loans guide covers the basics.
DSCR Calculator
Run the numbers in your market
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Oct 15, 2026
Prefilled with starting assumptions — enter your own rent or nightly figures, taxes, insurance, and HOA for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Oct 15, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Rent, nightly rate, occupancy, taxes, and insurance are editable estimates. Short-term rental figures are estimates only and vary significantly by season, property type, management approach, and local short-term-rental rules — confirm local regulations before relying on them. Qualifying income for short-term rentals varies by program — some use appraisal market rent, others use documented STR history or projections — and is confirmed in underwriting. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
Key Terms Defined
Co-living (rent-by-room): A rental model where individual rooms are leased to separate tenants who share kitchens, baths, and common areas.
DSCR (debt service coverage ratio): Monthly rent divided by the property’s monthly PITIA. At 1.00, rent equals the payment.
PITIA: Principal, interest, taxes, insurance, and association dues. It is the full monthly housing obligation the lender compares rent against.
Market rent: The rent an appraiser concludes a unit would command in the open market, regardless of what a tenant currently pays.
Master lease: One lease between the owner and an operator, who then subleases rooms to individual tenants.
Rent roll: A table listing each unit or room, its tenant, lease dates, and rent.
Certificate of occupancy: The local sign-off that a building may be lived in as its stated use and unit count.
Should You Confirm the Program Accepts This Property Type First?
Yes, and do it before the appraisal. Eligibility for rent-by-room is a program-level overlay. Across Lendmire’s wholesale network, some lenders take a legally configured duplex with rooms leased individually, some want the leasing to look like a standard unit lease, and some exclude the use entirely. Ordering an appraisal before you know which camp a program sits in can mean paying for a report you cannot use.
So the first step is a conversation, not a document package. Describe the property plainly: two legal units, how many bedrooms each, whether each unit has its own kitchen and entrance, and how you lease. A broker who sees many lenders’ guidelines can tell you which programs fit and which to skip. Get the answer in writing, then order the appraisal.
One more screen applies. Manufactured homes, log homes, and barndominiums are not offered in the network, so a conversion built on one of those structures is out regardless of how it rents.
How Does the Lender Actually Read a Converted Duplex?
The lender reads two units, not six or eight rooms. The appraiser identifies comparable rentals for each unit, adjusts them, and reconciles one monthly market rent per unit. Fannie Mae’s published Form 1025, the small residential income property report, instructs the appraiser to reconcile indicated monthly market rents into an opinion for each unit. DSCR loans are not agency loans, but lenders commonly borrow this form’s rent schedule as a rent document.
That matters because the one-unit rent schedule, Form 1007, is a different animal. Per Fannie Mae’s appraisal forms page, Form 1007 is for one-unit investment property. A duplex falls on the two-to-four-unit side, where the unit is the rent-reporting building block.
Here is how the pieces compare:
| Item | What the lender counts | What stays upside |
|---|---|---|
| Rent figure | One market rent per legal unit | Sum of all room leases |
| Rent source | Often the lower of lease or appraised rent | Room premiums above market |
| Value basis | Comparable duplex sales | Co-living income |
| Cost basis | PITIA only | Utilities, turnover, furnishing |
On many files the lender credits the lower of the in-place lease and the appraiser’s market rent. That is typical, not universal, and each program sets its own rule.
A hybrid works the same way. If one side is co-living and the other is a standard long-term rental, you still get two unit-level rent opinions.
What Does a Worked Example Look Like?
Run the numbers on a modeled duplex, using hypothetical inputs and no sourced market data. Say each side has four bedrooms leased individually. Stacked together, the room leases suggest a coverage ratio around 1.6x against the full monthly obligation. The appraiser, however, reconciles one market rent per unit, and those two figures together support coverage near 1.15x.
The lender sizes the loan on the 1.15x story. The gap between 1.6x and 1.15x is your upside, not your qualifying income.
Now stress it. If one unit’s rent opinion came in lower and the file landed near 1.00x, you would be at the edge of where select programs start. A separate select-lender path takes coverage below 1.00, with leverage and terms adjusted. Neither one is a promise; each depends on lender guidelines, credit, reserves, and property review.
Then stress the operations. Assume two rooms sit empty for a stretch. The DSCR calculation does not move, because the appraiser’s market rent does not care. Your actual cash does. That is the honest gap in this strategy.
How Do You Build the Conversion Evidence File?
Build it before the lender asks, because a conversion without paperwork reads as a risk. The lender wants to know the building is legally a duplex and that the rooms are legal bedrooms. A short, organized file answers both.
| Document | What it proves | When to gather |
|---|---|---|
| Permits and final sign-offs | Work was authorized and inspected | Before submission |
| Certificate of occupancy | Legal use and unit count | Before submission |
| Before and after floor plans | What changed and where | Before appraisal |
| Egress and life-safety notes | Bedrooms meet code | Before appraisal |
| Insurance matching real use | Coverage fits room-by-room leasing | Before submission |
| Entity documents | Vesting, subject to lender program eligibility | With application |
The certificate and permit file is a practical recommendation, not a rule printed in any single guideline. Still, appraisers treat legal status as material. Properties with illegal second units are handled differently in agency appraisals. That is agency context only, but it shows why a duplex carved out of a single-family house needs proof it is a legal two-unit property. Whether a given DSCR program accepts it is a program question.
How Should You Lay Out the Rent Roll?
List every room, grouped by unit, and explain every difference in rent. A clean rent roll lets the underwriter see the structure in thirty seconds. Include the unit, room, bedroom and bath access, approximate size, furnished or unfurnished, rent, lease start and end, and the deposit received.
Add one line of logic wherever rents differ. A room with a private bath renting above one sharing a bath is easy to understand. Unexplained gaps invite questions.
Attach the support: executed leases, bank statements showing rent and deposit receipt, and any house rules. Where a program allows room leases, these carry weight. Where it does not, they still help the appraiser and underwriter understand the operation.
Which Lease Structure Reads Best?
The lease structure changes how the underwriter sees your income. There are three common versions.
| Structure | How the lender reads it | Watch for |
|---|---|---|
| Individual room leases | Several tenants per unit | Program may cap or ignore room income |
| Joint lease per unit | Looks like a standard unit lease | Tenants share liability |
| Master lease to operator | One tenant, one lease | Operator strength gets reviewed |
A joint lease per unit maps most cleanly onto the per-unit rent opinion. A master lease can work, but the lender then underwrites the operator, and some programs want that operator to have a track record. Individual room leases give you the most control and the most scrutiny.
There is no single right answer. Pick the structure that matches how you really operate and that a confirmed program accepts.
DSCR vs. conventional financing
There are two common ways to finance an investment property, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
What If the Property Has No Operating History?
A newly finished conversion has no rent history, so the appraiser’s market rent decides. That is not a dead end. It means your evidence file and your lease-up plan carry more weight. Show signed leases if you have them, a realistic timeline for filling the rest, and reserves that cover the gap. Some programs also attach conditions about leases in place before or after closing, so ask early.
Do not lean on nightly or furnished-by-the-night use to fill the gap. The appraisal rent schedule estimates traditional long-term leasing rent, so nightly stays do not map onto it. True short-term rental underwriting is a separate path, typically with its own hosting history and leverage limits.
Should You Disclose the Strategy and Offer a Whole-House Fallback?
Disclose it. Tell the lender how you plan to operate, and do not dress co-living up as a standard rental. A surprise discovered at appraisal or insurance review costs more than an honest conversation up front.
Then run the two-track test. Ask whether this duplex, leased as two ordinary units, still clears the program’s coverage floor with the leverage you want. If it does, room income is upside and the file survives even if the underwriter ignores it. If it does not, adjust the structure: a larger down payment, lower leverage, or a program built for thinner coverage. A larger down payment lowers the monthly obligation and can lift the ratio, but it never erases leverage caps, credit floors, reserve rules, or property eligibility.
Here are the network ranges to plan around, as typical guidance subject to lender guidelines. Purchases usually land at 75%-80% LTV on an investment property, and cash-out refinances top out around 75% LTV. Credit floors start at 620 in parts of the network, with most programs wanting about 660 and 700+ opening the strongest leverage. Reserves commonly run about 6 months of PITIA, stepping up to about 9 months on larger loans. Coverage starts at 1.00 for select programs, which is a floor for those programs and not a universal standard.
Expenses, Insurance, and Occupancy Limits
Budget for what DSCR ignores. Shared utilities, internet, common-area upkeep, turnover, furnishing, repairs, vacancy, and management all sit outside the ratio. Co-living tends to carry more of these than a standard rental, since tenants turn over more often and showings multiply. Decide up front whether you self-manage or hire a manager, and put that plan in the file.
Occupancy rules are local. A city may cap unrelated occupants per household, treat the use as a rooming house, or have no clear rule at all. Some investors only find out after a neighbor complains. Check your own municipal code, and confirm your insurance policy matches the real use. There is no national limit to rely on.
Why Do These Files Stall?
Most stalls trace back to a short list of causes. Each has a fix.
| Reason | Fix |
|---|---|
| Program excludes rent-by-room | Confirm acceptance before appraising |
| Conversion lacks permits or CO | Close the paperwork gap first |
| Room income expected to count | Underwrite on per-unit market rent |
| Coverage thin on whole-house rent | Lower leverage or adjust the structure |
| Insurance mismatched to use | Update the policy to match operations |
One pattern shows up often on files like this. Investors lead with the room-sum income, the appraiser reconciles two unit rents, and the file looks weaker than the investor expected. Building the package around the per-unit number avoids that disappointment.
One timing note on appraisals. Per a Fannie Mae and Freddie Mac UAD 3.6 FAQ, the legacy appraisal forms are being replaced by one redesigned report for agency submissions, and an appraisal-practice explainer from Epic Appraisal reports a November 2, 2026 mandatory date. That change concerns agency delivery. How a given DSCR program handles its rent schedule is something to confirm with the program.
Pre-Submission Checklist
- Program acceptance of rent-by-room confirmed in writing.
- Legal duplex status and certificate of occupancy documented.
- Permits, sign-offs, and before and after floor plans in one file.
- Rent roll by unit and room, with rent differences explained.
- Executed leases and bank statements showing deposits.
- Insurance that matches the actual use.
- Entity documents, subject to lender program eligibility.
- Reserves documented.
- A coverage check on whole-house rent alone.
- A written operating and management plan.
Tax treatment varies; consult a qualified professional.
Frequently Asked Questions
Can room-by-room income count toward DSCR?
Sometimes, but do not plan on it. Many programs credit one rent figure per unit, often the lower of the lease and the appraiser’s market rent. Treat the extra room income as upside until a specific program confirms otherwise.
Does a duplex change anything compared with a single-family co-living house?
Yes. A duplex is appraised on a two-to-four-unit report with a rent opinion per unit, while a single-family home uses the one-unit rent schedule. Rooms inside each unit sit below that level, so you present two coherent units.
Do I need a certificate of occupancy for a converted duplex?
Plan on having your local sign-off and permit file ready. Appraisers treat legal status as material, and a duplex made by carving up a single-family home may not be a legal two-unit property. Whether a program takes an unpermitted conversion is a program decision.
Can projected rent support a vacant or newly renovated duplex?
Often the appraiser’s market rent carries a vacant property, since there is no history to use. Some programs attach conditions about leases in place before or after closing. Ask the program before you order the appraisal.
Should I use individual leases or a master lease?
It depends on how you operate and what the program accepts. A joint lease per unit maps most cleanly to per-unit rent, while a master lease means the lender evaluates the operator. Individual leases give you control but draw the most scrutiny.
Next Step
If you are buying or refinancing a rental property and want to see how the numbers work, Lendmire can help you compare DSCR loan options based on the property income, credit profile, leverage, and investor goals. Lendmire is a broker that arranges financing through select lenders in its wholesale network across 41 markets, including Washington, D.C. Qualification is subject to lender guidelines and is not a commitment to lend. For a related look at new construction or renovation timing, see Lendmire’s piece How a DSCR Lender Reads Rent on a Recently Converted Rental Property.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
A DSCR-focused mortgage broker, Lendmire (NMLS# 2371349) places investor financing across 41 markets — 40 states plus Washington, D.C. — with DSCR eligibility generally reviewed by the lender on property cash flow instead of tax returns, subject to lender guidelines. Scotsman Guide named Lendmire a Top Mortgage Workplace in 2025 and 2026.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Fannie Mae Form 1025 (Freddie Form 72)
2. Fannie Mae Selling Guide B4-1.2-01
3. Epic Appraisal UAD 3.6 explainer
This article is part of Lendmire’s DSCR loan program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: How to Re-Quote Rental Insurance When a Renewal Sinks Your DSCR · How to Shop and Document Rental Insurance Before a DSCR Loan · Can You Refinance a Rental Awarded in Divorce With a DSCR Loan?
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Required disclosures. Lendmire (NMLS# 2371349) operates as a licensed mortgage broker, not a direct lender or depository. The discussion in this article is general in nature and should not be relied upon as financial, legal, or tax advice — every investment scenario is unique and should be reviewed by a qualified professional. Any loan inquiry is subject to lender underwriting, and this article is not a commitment to lend or a guarantee of approval. Mortgage rates, loan terms, and program guidelines vary by borrower, property, and state, and may change without notice. Equal Housing Opportunity. Verify licensure at NMLS Consumer Access.