Complete Guide For A Hard Money Loan On Single-family Properties
Underwriting looks at purchase price, rehab scope, and after-repair value first, and the borrower’s file second.

 Lendmire Research
Underwriting looks at purchase price, rehab scope, and after-repair value first, and the borrower’s file second.
A standalone HELOC underwrites your personal credit and income. A DSCR cash-out refinance underwrites the property’s rent.
– The investment-property equity line caps at 70% CLTV and a $500,000 program ceiling, regardless of whether the borrower’s credit sits at 700 or 720.
Underwriting looks at what the 1099s actually show, not the net figure left over after business write-offs.
Twenty-four months of statements smooths out a bumpy income year that twelve months alone might penalize.
That’s a fundamentally different product from a DSCR loan, which sizes the loan around the property’s rental income instead of the borrower’s.
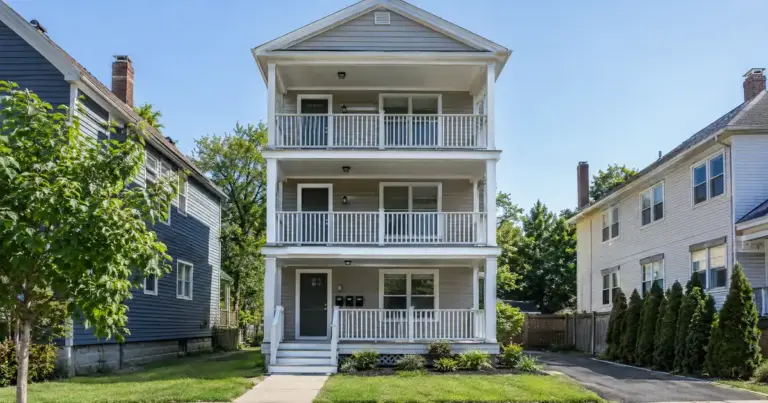
Whether the file runs through consumer disclosure rules or business-purpose rules depends entirely on whether the owner lives in one of the units.
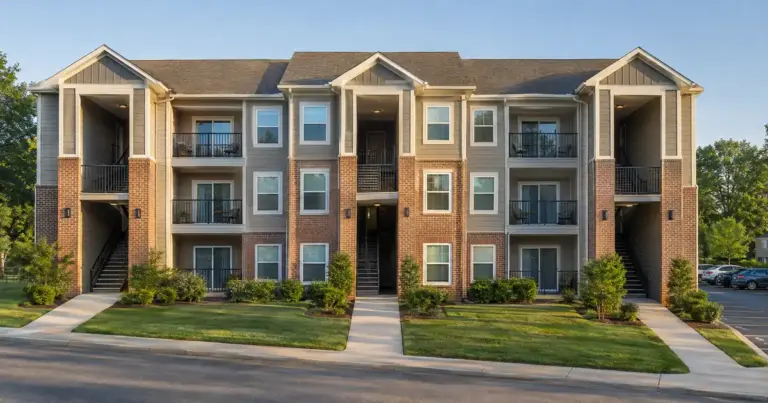
Multifamily 5+ Bank Statement Loan Complete Guide: what borrowers need to know about bank-statement and self-employed financing, from Lendmire.
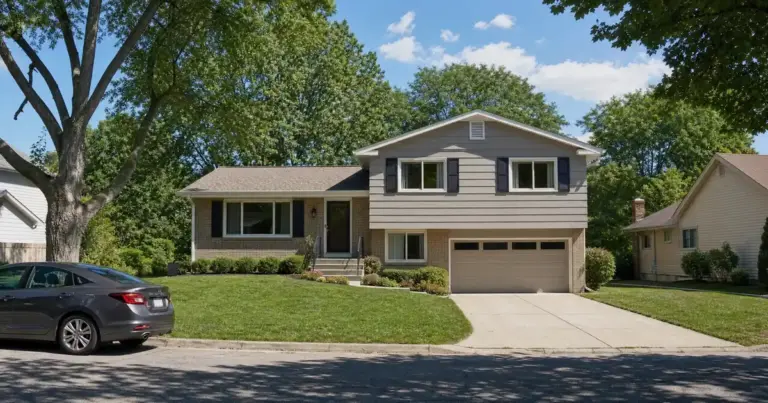
Whether the file is treated as a consumer mortgage or a business-purpose loan depends entirely on who is going to live in the house.
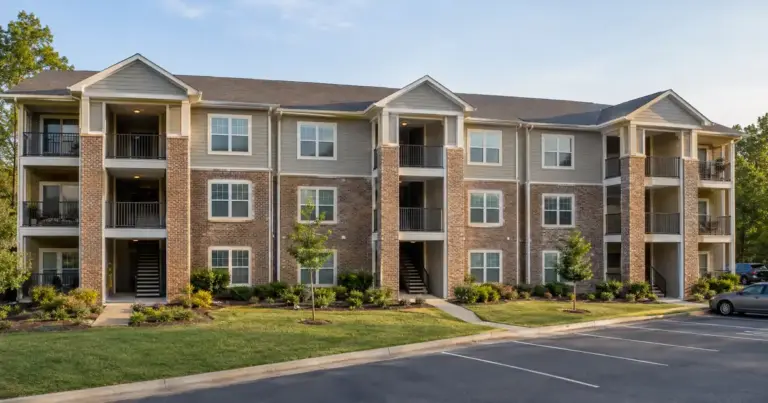
It exists because five-plus unit buildings get appraised and underwritten differently than a duplex or fourplex the moment they cross that unit-count line.
What beginners usually mean is no extra personal collateral stacked on top of the deal, and that distinction changes how a file gets built from day one.
Which one wins depends on whether you’re protecting a loan you already like or trying to pull the largest check the rental will support.
Most investment property equity lines cap around 70% combined loan-to-value, run a five-year draw period, and require roughly a 700 credit score.
Non-warrantable condo projects are eligible on some wholesale programs, which is the opposite of what conventional bank underwriting assumes.
The line is sized off the borrower’s credit and debt-to-income, never the rent the property collects.