Complete Guide For A DSCR Loan On Short-term Rental Properties
A ratio of 1.00 means the rent covers the payment exactly; above 1.00 means there’s cushion.

 Lendmire Research
A ratio of 1.00 means the rent covers the payment exactly; above 1.00 means there’s cushion.
Rent divided by the payment produces the ratio; clear it, and the file moves forward on the strength of the property.
The rest of this guide walks through the mechanics, the variations, and the places where the general rule breaks.
Getting the distinction right before applying saves a file from stalling mid-underwrite.
It’s a personal-income product built for the borrower, not the property, which makes it a different tool from a DSCR rental loan.
The real skill isn’t finding a lender — it’s understanding how the underwriting works well enough to vet any lender against it.
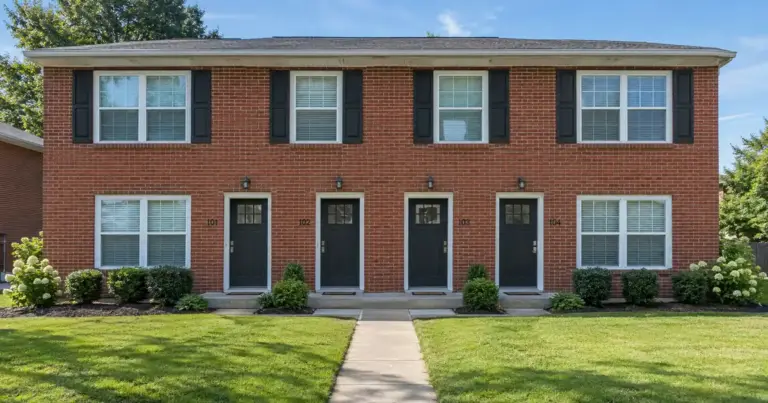
– 2-4 unit properties use a different appraisal form than single-family rentals — one that combines valuation and rental income into a single report.
It’s a real, select-lender path, not a marketing term, and it exists alongside standard DSCR programs that still require rent to cover the payment.
The underwriting math just adds HOA or condo association dues to the usual payment stack before comparing it against rent.
– A 2-4 unit DSCR loan uses one blended payment (PITIA) against combined rent from every unit in the building — not a separate loan per unit.
The tradeoff shows up in two places: the DSCR math on the new payment, and any prepayment penalty still ticking on the old loan.
Terms typically run 6 to 18 months, credit floors start around 620, and the strongest leverage goes to investors with a track record of finished projects.
Investors who understand which tier applies to their deal walk into underwriting with realistic expectations instead of guesses.
– Hard money underwriting starts with the property and the plan, not the paycheck.