Investment Property Loans in Tampa, FL: How BAH Rent Floors Clear DSCR Math

DSCR investment property loans in Tampa, Florida — East Tampa, Seminole Heights, and USF multi-unit math for purchase-side coverage ratios.

 Lendmire Research
DSCR investment property loans in Tampa, Florida — East Tampa, Seminole Heights, and USF multi-unit math for purchase-side coverage ratios.

DSCR investment property loans in Philadelphia, Pennsylvania — qualify on the property’s projected rental income rather than personal W-2 income.

East Point’s 9-10% yield beats Kirkwood’s 0.7x coverage. DSCR investment property loans in Atlanta, Georgia — neighborhood math, cash-flow analysis.
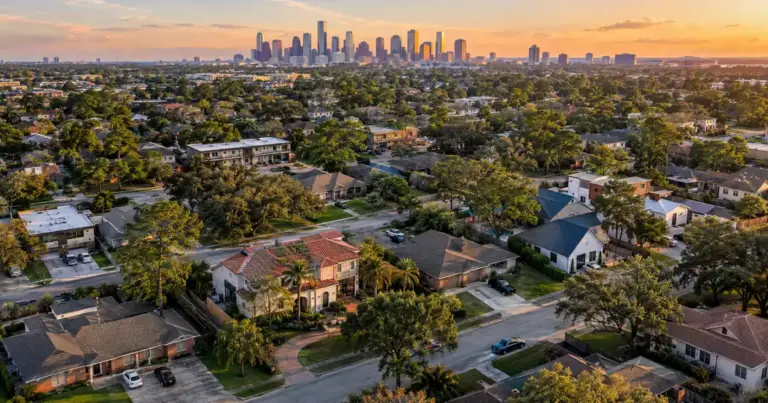
Compare investment property loans Houston Texas investors use, by submarket: Northeast, Southwest, Third Ward. Get a DSCR scenario quote from Lendmire.

DSCR investment property loans in Dallas, TX: Mesquite and Oak Cliff pencil at 1.10-1.40x coverage vs. Uptown’s tight condo math. See the submarket data.

DSCR investment property loans in Arlington Heights, IL — two-flat vs SFR coverage math, Metra corridor demand, and 75% LTV purchase terms.
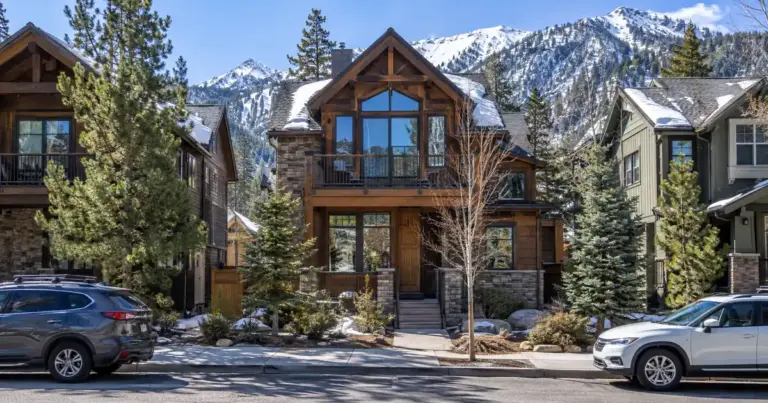
Investment property loans Big Bear Lake California: see where DSCR coverage works, from Big Bear City duplexes to the Village. Request a Lendmire quote.

DSCR investment property loans in Honolulu, Hawaii — qualify on the property’s projected rental income rather than personal W-2 income.

A DSCR appraisal does two jobs at once — it values the property and it establishes the rent a lender will actually use to qualify the loan.

No — traditional down payment assistance (grants, forgivable seconds, HFA programs) does not work with DSCR loans, because those programs require

Yes — a DSCR loan qualifies against the rental property’s income, not the borrower’s paycheck, so an investor with no W-2, no employer, and no traditional
How Lenders Read Your DSCR — DSCR is not a pass/fail test.

Do Lenders Verify Employment on DSCR Loans: what investors need to know about DSCR financing — eligibility, coverage, and loan structure, from Lendmire.

Most DSCR files still ask for some cushion of cash after closing — commonly around six months of PITIA, sometimes more on larger loans.

Most DSCR programs want a credit score somewhere in the 660-680 range, with a hard floor around 620 on select programs in the network.