2-4 Unit DSCR HELOC: Complete Guide
One is a standalone equity line reviewed on your own income and credit, not the property’s rent.

 Lendmire Research
One is a standalone equity line reviewed on your own income and credit, not the property’s rent.
True rent-based qualification on a single-family rental almost always shows up in a different structure: a first-lien DSCR cash-out refinance.
It solves a real documentation problem — but it’s a narrower tool than most STR owners expect.
Complete Guide For A 1099-only Loan On Multifamily 5+ Properties — what borrowers need to know, from Lendmire.
But the condo runs through its own separate review.
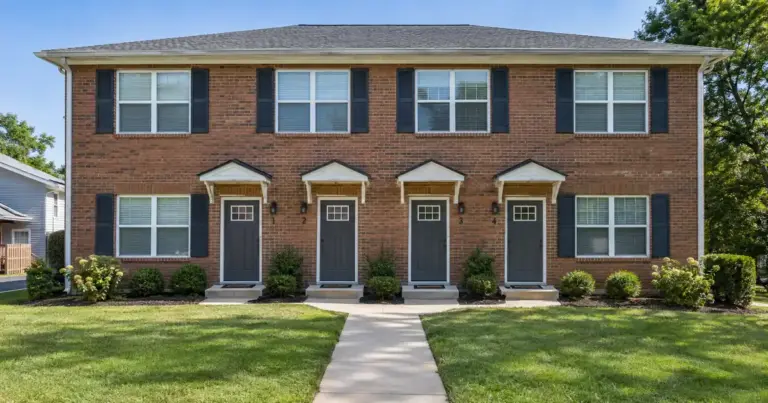
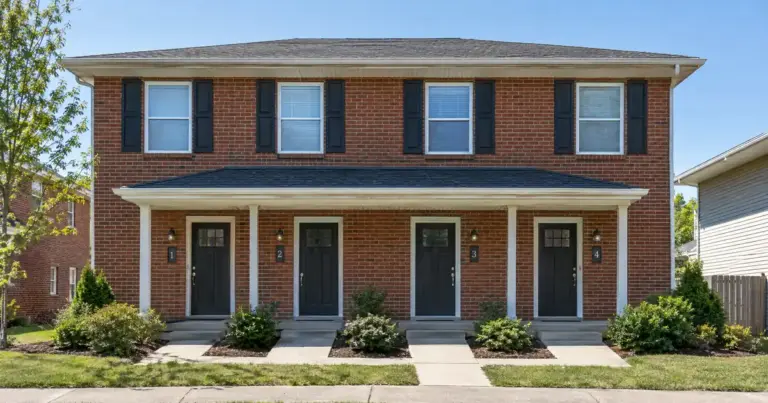
It fits self-employed buyers who earn on 1099s and want a duplex, triplex, or fourplex. Occupancy decides everything.
One is the five-unit threshold that reclassifies a property from residential to commercial multifamily.
The longer window smooths that swing into one averaged monthly figure, but it also dilutes a strong recent year with an older, weaker one.
Either file can sink the deal on its own, regardless of how strong the other one looks.
It’s a consumer mortgage, which matters most when one unit is owner-occupied.
Bank statement underwriting solves a consumer-mortgage problem tied to a four-unit ceiling.
The borrower’s income gets built from deposit averages instead of tax returns.
An underwriter averages the deposits, applies an expense factor to strip out business costs, and treats what’s left as qualifying income.
For STR hosts specifically, the mechanics get complicated fast, because what lands in the bank account is rarely the same number as gross booking revenue.
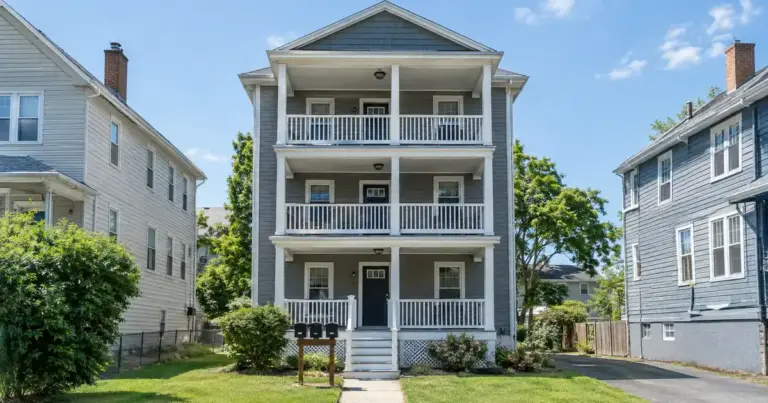
2-4 Unit Bank Statement Loan Complete Guide — A bank statement loan lets you buy or refinance a 2-4 unit property using 12 months of bank