Apartment Investment Property Refinance Loans Financing
Get that fork wrong at the start, and the wrong appraisal form, the wrong income concept, and the wrong lender end up on the file.

 Lendmire Research
Get that fork wrong at the start, and the wrong appraisal form, the wrong income concept, and the wrong lender end up on the file.
The vehicle that does this is a DSCR loan, built around the rent-to-payment math on the specific property, not a scan of the owner’s checking account.
– Bank statement HELOCs don’t come from one dominant lender — they come from three distinct provider categories, each built for a different borrower.
– Underwriting runs on credit tier, combined loan-to-value, and debt-to-income — not a personal tax-return package.
A private money investor lends money and expects a fixed return no matter how the property performs.
Which method applies depends on the loan program, your ownership stake in the business paying you, and how long you’ve been receiving 1099 income.
If your real goal is pulling equity out of a rental, a DSCR cash-out refinance is often the cleaner tool. No law bans it.
The real friction isn’t whether the money is allowed; it’s proving where it came from and when it landed in the account.
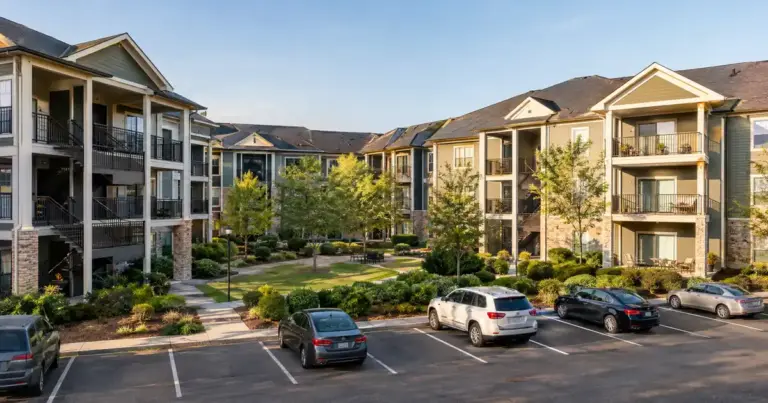
Apartment Investment Property Refinance Loans — Refinancing an apartment property splits into two different worlds depending on unit count.
It is a separate product from a DSCR loan, which is why so many investors get confused mid-project.
Renovating A Property Into An Airbnb With Hard Money — This is a two-loan play, not one.
Financing A New Construction Airbnb — Financing a new construction Airbnb almost never means one loan.
– DSCR loans qualify on the property’s rental income divided by its monthly obligation — not on tax returns or W-2s.
Here’s what to know before you start shopping listings: – DSCR loans qualify the property, not your paycheck — rent covers the payment, or it doesn’t.