Can You Refinance A Hard Money Loan?
Yes. Refinancing out of a hard money loan is the normal, expected exit for an investor who wants to keep a property as a rental instead of selling it.

Yes. Refinancing out of a hard money loan is the normal, expected exit for an investor who wants to keep a property as a rental instead of selling it.
Paying off a primary-residence credit card balance generally doesn’t fit this box.
The new loan pays off the hard money balance and moves the deal from short-term bridge debt into permanent financing.
Get the spread wrong, or misjudge the seasoning clock, and part of your capital stays stuck in the property.
Seasoning, appraisal, and the property’s rental income all shape what actually comes out at closing.
The appeal is real: private lending yields have long drawn investors who want income tied to real estate without the headaches of owning it.
The lender is underwriting the deal and the collateral, not the borrower’s paycheck. That’s the short version.
Terms typically run 6-18 months, payments are interest-only, and the loan comes due in one balloon payment when you sell or refinance.
How To Qualify For A Hard Money Loan — Qualification runs on the deal, not the borrower’s paycheck.
This guide walks through the mechanics, the qualification standards, and where the standard rulebook actually breaks down.
Underwriting centers on the property, the renovation plan, and the after-repair value — not your tax returns.
What changes isn’t the unit itself, it’s the building around it. A single-family house has one owner, one title, one set of liens.
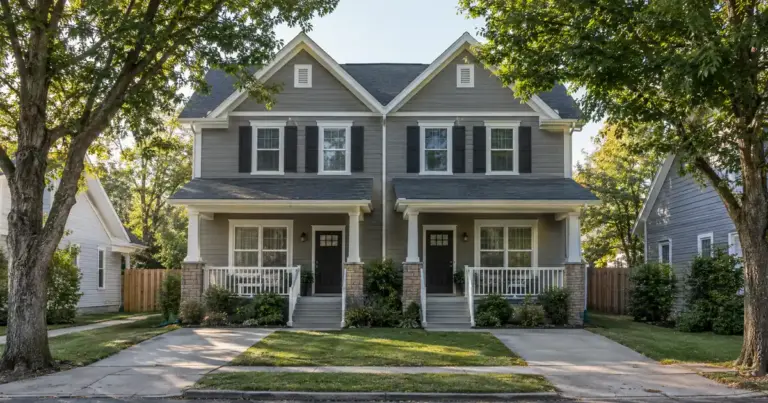
Terms run 6-18 months, interest-only, with no prepayment penalty.
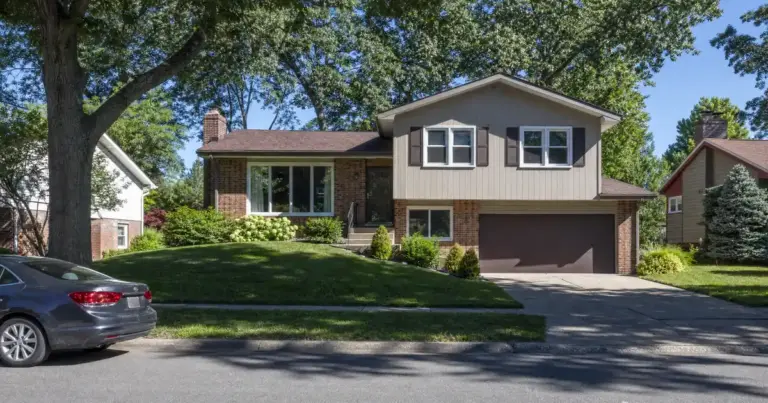
Underwriting looks at purchase price, rehab scope, and after-repair value first, and the borrower’s file second.
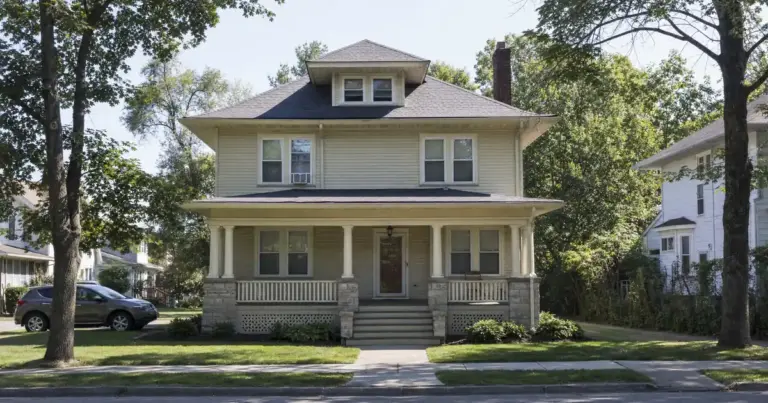
What beginners usually mean is no extra personal collateral stacked on top of the deal, and that distinction changes how a file gets built from day one.